Long-term care insurance

Make a plan for the care you may need.

Talk through care at home, assisted living, family support, and the role long-term care insurance could play.

Play video: Four Things to Review in Your Retirement Plan, 1:20
Watch · 1:20 Four Things to Review in Your Retirement Plan
Read the transcript

Hi, I'm Julianne Dickey, We Care Medicare, your Medicare insurance advocate for the Central Coast. When we sit down together, I don't just look at Medicare, I look at four things. One, health insurance.

This is usually Medicare coverage that gets you your doctors and helps pay the bills. Two, if you need care at home or in a facility, this protects your savings and it protects your family. Three, income versus growth.

Some annuities pay you a steady paycheck for the rest of your life, and others focus on growing your money. The right one depends on what you need. Four, do you want to leave a legacy?

Protect your assets? And these days, there are hybrid policies that combine long-term care and life insurance all in one. If you need care, you're covered.

If you never do, your family still gets the benefit. We don't have to figure it all today. We start where you are.

Give me a call and let's look at the whole picture together.

Keep watching

Life insurance and long-term care together.

Play video: Life Insurance and Your Legacy, 1:07

Life Insurance and Your Legacy 1:07

Read the transcript

I'm Julianne Dickey, We Care Medicare, your Medicare insurance advocate for the Central Coast. Life insurance isn't about dying, it's about the people who are living. There are a few different types of life insurance.

There's term life, which covers a set stretch of years when the need is biggest. Whole life covers you your whole life and it also builds cash value. There's another type of life insurance called universal life.

This combines whole and term life. There are hybrid policies that combine life insurance and long-term care coverage. You can use it for care if you need it and if you don't then your family gets the benefit.

Then there's final expense policies. They cover the goodbye, so your family doesn't have to think about it that week. Want to leave a legacy?

Protect what you've built? Let's design it on purpose. Give me a call.
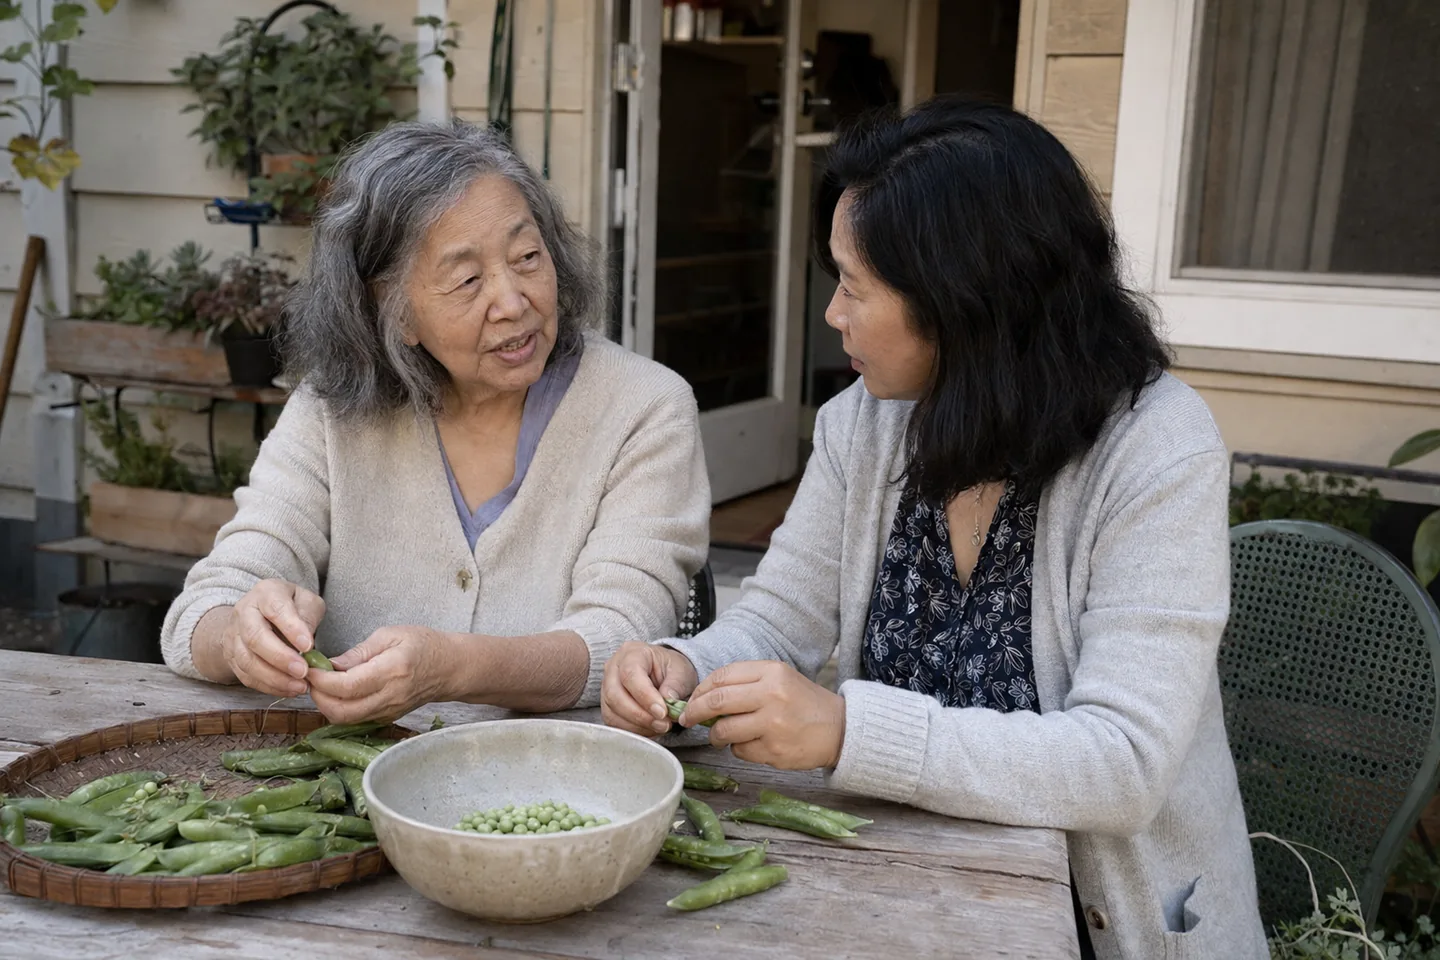
An older woman and her adult daughter preparing peas together on a porch

Care starts with a conversation

Begin with your preferences

Where would you want to receive care if everyday activities became difficult? Who could help, and for how long? These are personal questions before they are insurance questions.

Starting the conversation while you are healthy gives you and your family more time to consider options. For someone around 55, future care can be part of a broader retirement plan rather than an urgent decision.

What long-term care insurance is for

Long-term care coverage is designed to help with qualifying care needs under the policy's terms. It may address care at home, assisted living, or other covered settings. It is not the same as Medicare or ordinary health insurance.

Medicare covers certain skilled care when its conditions are met. It generally does not cover ongoing custodial care, such as long-term help with bathing, dressing, or other daily activities alone.

What to compare in a policy

  • What triggers eligibility for benefits.
  • Which care settings and services are covered.
  • The waiting or elimination period before benefits start.
  • Daily or monthly benefit amounts and the benefit period.
  • Inflation protection and future purchasing power.
  • Premiums, possible changes, exclusions, and underwriting.

Hybrid alternatives to traditional policies

Traditional long-term care insurance is not the only option today. Some life insurance policies and annuities now include features that can help cover qualifying care costs, which is one reason people consider them alongside or instead of a standalone policy.

Julianne can explain the differences as they apply to you. See the life insurance and annuities pages for the products involved.

Include the people who may help

Family members may have work, health, or caregiving responsibilities of their own. Discuss what support they could reasonably provide, what paid care might cost, and how decisions would be made.

Home health care planning, assisted living, and caregiver support deserve their own attention. Julianne can explain the insurance options she offers while you work through the larger family conversation.

Talk it through

Your questions belong here.

Julianne can help you understand how this applies to your own coverage and plans.

Call Julianne

No fee for Medicare guidance. Julianne is paid directly by insurance companies.

A conversation is a good place to start

You don't have to work this out alone.

Tell Julianne what's changing in your life. Together, you can work through your coverage questions and next steps.

Contact Julianne

What would you like help with?

Send a message or request a conversation. Julianne will follow up with you directly.

(805) 441-9093
support@wecaremedicareplans.com

Monday through Friday
8:00 am to 5:00 pm
Closed Saturday and Sunday

Serving San Luis Obispo and Santa Barbara counties, from Paso Robles to Lompoc. Meetings at your home or an agreed location. Before any in-home appointment, California law requires 24 hours’ written notice, which Julianne sends you in advance.

Name, email and phone are required.

Please do not include medical information, prescriptions, Medicare identifiers, Social Security numbers, or other sensitive personal information.

We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Your information goes to Julianne Dickey and is used to respond to your request. It is not sold. Read our Privacy Policy.